Commission Accruals and ASC 606 Compliance for Finance Teams
Finance teams need deal-level commission data to classify and amortize costs under ASC 606.
Commission accruals under ASC 606 require more than an accurate payout total. For mid-market RevOps and Finance teams, commission software must produce deal-level attribution, dated rule versions, and locked audit evidence so that eligible commissions can be classified, capitalized, and amortized reliably. Compliance begins in the commission calculation workflow.
What ASC 606 actually changed about how commissions are recorded
ASC 606, paired with ASC 340-40, changed the accounting treatment of eligible sales commissions from a period expense to a contract cost asset. Previously, a commission on a multi-year contract could hit the income statement in a single period. Under the capitalization model, that cost first appears on the balance sheet and then flows into expense through amortization over its period of benefit. Finance must distinguish the obligation to pay a rep from the timing of the expense associated with obtaining the contract.
That distinction connects commission accounting to the economics of the customer contract. The revenue recognition framework governs when revenue is recognized, while the contract acquisition cost follows the benefit it generates. Commission data must show how to classify the asset, set an amortization schedule, and make adjustments when the contract changes. A payroll record can establish what a rep received, but it does not by itself establish how that payment belongs in the financial statements.
Which commissions get capitalized and which get expensed immediately
Classification begins with whether the cost is incremental and recoverable. An incremental cost is a cost incurred only to win a specific contract, while recoverability depends on the cash flows expected from that contract in the future. A variable commission paid for closing a deal usually meets the incremental test. Base salaries and general marketing costs do not. Finance must then assess the benefit period and its consistently applied policy for the one-year practical expedient, under which qualifying short-term commissions can be expensed immediately.
Commissions for winning new customers on multi-year deals usually qualify for capitalization. Upsell and expansion commissions representing new performance obligations, and partner commissions tied to specific contract acquisition, can also qualify. Renewal commissions require a separate judgment about whether they are commensurate with the initial commission. For example, a rep might earn a materially lower rate at renewal than at initial close because retention requires less acquisition effort. That difference may justify amortizing the initial commission over a longer period that includes expected renewals, provided the rationale is documented.
By contrast, an essentially unchanged renewal commission rate limits amortization of the initial commission to the initial contract term. The distinction changes the duration of the asset. It therefore cannot be left implicit in a payout formula or inferred from the rep’s total earnings. SPIFs, bonuses, draws, recoverable advances, and clawbacks also need separate classification rather than automatic treatment as acquisition commissions. A usable transaction record distinguishes capitalizable costs, non-capitalizable incentives, renewals, expansions, and reversals before those transactions enter the accounting workflow.
How to set the amortization period and document the rationale auditors will demand
Once a commission qualifies for capitalization, finance must work out how long its benefit lasts. One approach uses the initial contract term plus renewals that are highly likely. Another uses how long the customer relationship is expected to last, backed by historical retention data, which takes more analysis and updates over time. The chosen period must account for churn, renewal patterns, expansion rates, product lifecycle limits, competitive dynamics, and switching costs where those factors affect the expected benefit.
Auditors need evidence for the chosen period, including renewal rate analyses and customer lifetime data. ASC 340-40-35-2 requires updates when the expected timing of transfer changes significantly, including changes associated with retention, renewal patterns, or commission structures. The standard also allows an approach based on the underlying software platform’s life, provided that life is consistently longer than estimated customer life. Whichever basis is used, the documentation must state the chosen duration and explain why it fits the business.
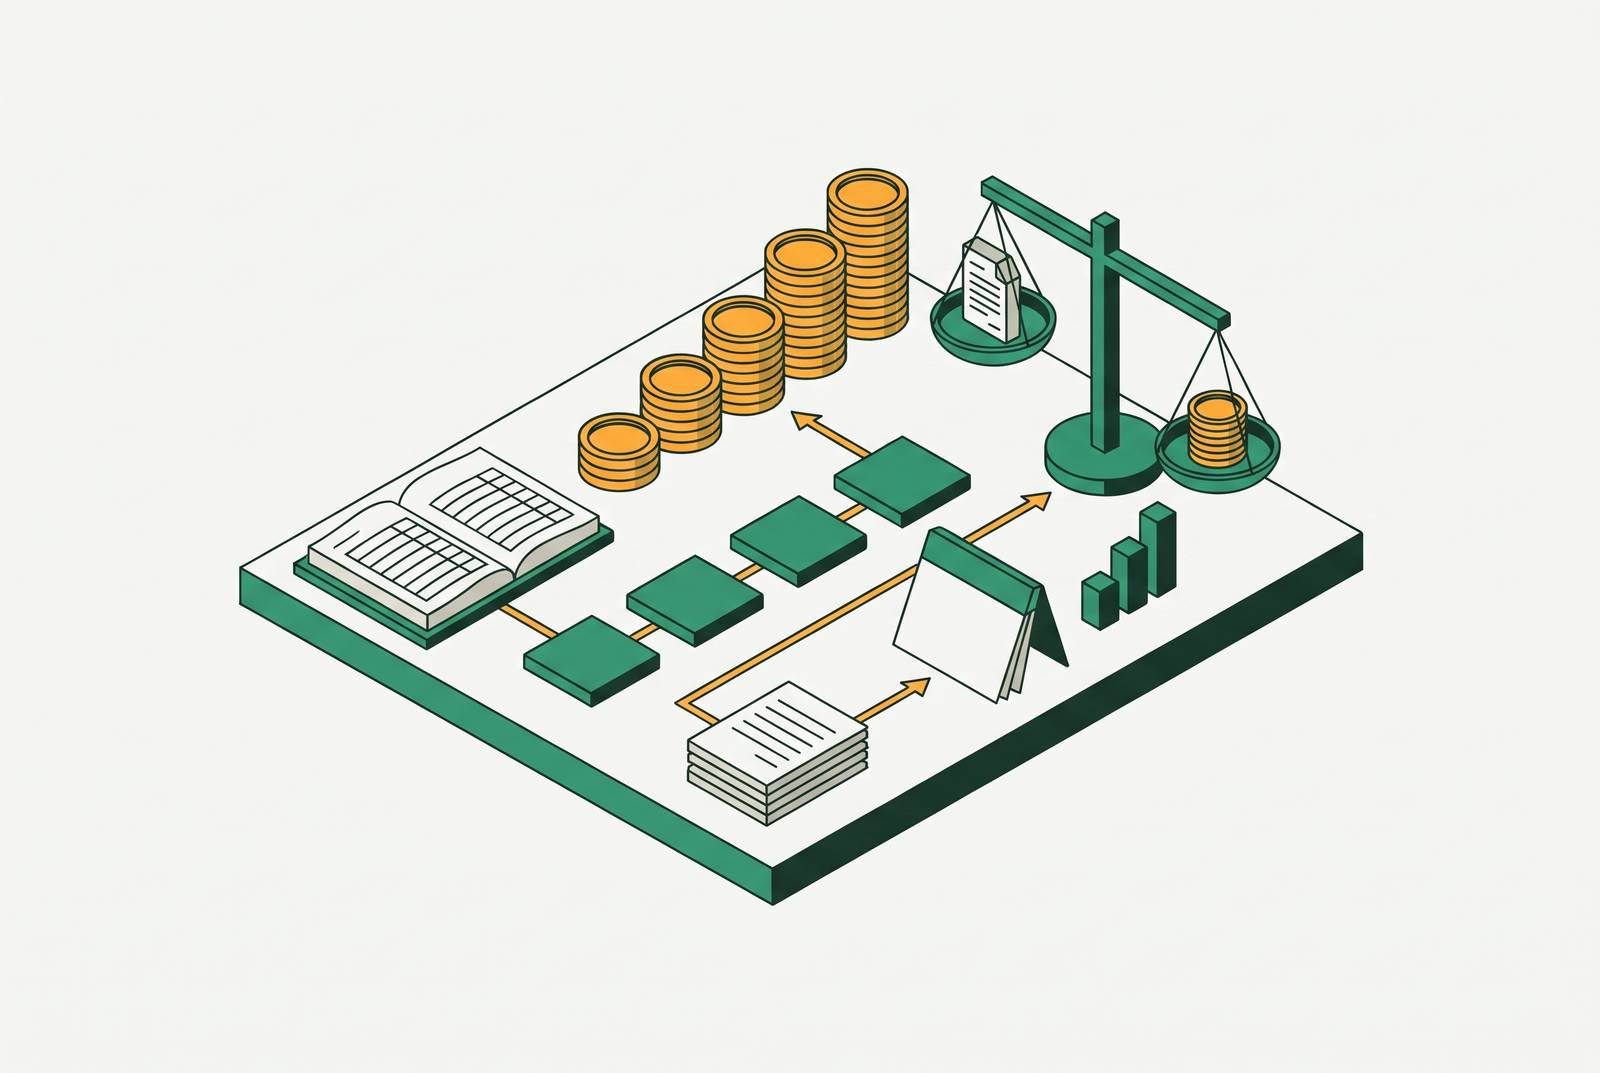
For a qualifying commission on a multi-year acquisition, the entry sequence begins with a debit to the deferred commission asset and a credit to cash or commission payable. Monthly amortization then debits commission expense and credits the deferred commission asset. A contract modification requires an additional assessment and adjustment. If the modification changes duration or the revenue basis, the related asset balance and amortization schedule must reflect that change. This sequence makes the documentation practical, because each entry depends on an identifiable contract, an approved classification, and a supported benefit period.
Why the accrual timing problem creates compounding reconciliation risk at quarter-close
Finance often estimates commission liabilities before the final payout calculations are ready. For simpler transactional commissions, expense accrual follows the period of the related sale, while eligible acquisition costs require capitalization and amortization over their benefit period. The liability estimate must therefore support more than payroll. How accurate that estimate is affects the amount added to the deferred commission asset and the expense recognized later. When the estimate changes, the accounting consequences extend beyond a correction to the rep’s payment.
Commission plans make those estimates structurally fragile. Quota accelerators can concentrate in the final days of a quarter, while territory changes can shift deal credit after an initial estimate. Contract amendments can alter transaction prices, and post-cutoff refunds can trigger clawbacks. At true-up, finance may need to revise the liability, capitalized additions, amortization schedules, and period expense, with documentation supporting the correction as well as the original entry.
An aggregated payout total conceals the information needed to make those revisions. Finance may reconcile the total to payroll without being able to identify which contracts produced it. That is a different kind of reconciliation failure. Without deal-level attribution, the team must reconstruct which assets and schedules need adjustment, often while other close work is underway. Manual amortization waterfalls, inconsistent classifications, and repeated exports and transformations compound the workload as compensation plans become more sophisticated.
How spreadsheet-based commission processes structurally undermine ASC 606 compliance
Spreadsheet-based processes often roll up deal-level calculations into totals for each rep for payroll. That aggregation removes the contract links needed for capitalization and subsequent adjustments from the output finance receives. A correct total is therefore an incomplete accounting record. Without the underlying attribution, finance cannot reliably assign the commission asset to its contract, select a contract-supported amortization period, or adjust the asset when the contract changes or terminates.
Historical rule versioning creates a second problem. Rates, accelerators, and territory assignments change, but historical calculations must remain reproducible under the rules that applied at the time. Finance needs dated rule configurations as well as formula history. A prior spreadsheet may contain a number without establishing the effective rule set that produced it. Reconstructing that context from files and recollection leaves finance with an explanation assembled after the event and a calculation it cannot reproduce.
The same distinction applies to approval evidence. A workbook edited, corrected, and re-saved throughout a quarter cannot reliably establish that its current figure is the figure originally calculated and authorized. Auditors require transaction-level support for both capitalization and amortization. Missing evidence can turn an otherwise routine request into a reconstruction exercise, while material misstatements can affect lender relationships, investor due diligence, financing rounds, and a future sale valuation. Spreadsheet skill does not restore the attribution, versioning, and immutable history that the process failed to preserve.
What commission software for mid-market RevOps and Finance teams must provide
Commission infrastructure must preserve accounting evidence where calculations originate. Every payout needs a traceable link to the contract, customer, and deal event that generated it. That link is the foundational accounting unit. It supports capitalization, benefit-period assignment, and adjustments associated with churn or contract changes. Historical rules must also be stored as structured configurations with effective dates so that a past calculation can be reproduced exactly.
An immutable audit trail must record the deal data, active rule version, calculation timestamp, and authorized approvals for each payout period. These records turn a compensation result into verifiable evidence. Beyond calculation, the platform must support transaction tags for acquisition costs, renewals, expansions, and clawback reversals, together with period-based amortization schedules. Datasets ready for export must keep that structure when they move into financial systems. Otherwise, finance inherits the same manual transformation problem in a different interface.
EasyComp’s ASC 606 accounting guide describes two approaches to that downstream workflow, namely integrated waterfall management and transaction-level exports. The integrated approach maintains beginning balances, capitalized additions, monthly amortization, adjustments, and ending balances by reporting period. The export approach supplies transaction detail with ASC 606 category mappings to systems including NetSuite, Sage Intacct, Oracle, SAP, and Microsoft Dynamics, or to custom financial models. These approaches serve different accounting system arrangements. The relevant comparison is whether each preserves the evidence finance needs.
The month-end close workflow finance teams should build around commission data
Finance teams can evaluate their current close against a workflow that begins before month-end. Commission calculations for the period should be finalized, approved, and locked before they feed the close. Unresolved calculations create adjustments that cascade into accounting entries. Transaction classification should already be embedded at the point of calculation, distinguishing capitalizable acquisition costs, non-capitalizable payments, renewals, expansions, and clawback reversals. Retrospective tagging in a separate workbook defeats the purpose of a structured source record.
Once the calculations are locked, finance should update the deferred commission waterfall. New eligible commissions add to the asset balance, the period’s amortization becomes expense, and contract modifications that change the duration or revenue basis require changes to the existing balances and schedules. Terminations, amendments, and expansions must be tracked through a structured process that gets the changes to accounting without relying on someone to remember to pass them on. A revised contract does not update the commission asset merely because the commercial record has changed.
Deal-level commission records should reconcile to CRM records for the underlying deal and to payroll for the payout amount. A payroll match establishes the payment total, while the CRM comparison supports the contract attribution used in classification and amortization. Structured records make discrepancies identifiable at the transaction level rather than leaving finance to investigate an unexplained difference between totals.
The audit package should then assemble transaction detail, category mappings, amortization schedules, and locked approval logs into exportable reports. This step should not require rebuilding the calculation history. Quarterly, finance should review retention rates, renewal patterns, and commission structure changes that could affect amortization assumptions, documenting any revisions to the supporting rationale. Both depend on information captured throughout the commission workflow.
How accurate commission data reduces audit exposure and builds cross-functional trust
When classification, calculation inputs, rule versions, and approvals remain attached to each transaction, finance can provide an evidence-backed export, avoiding manual reconstruction of the history. That reduces audit work and exposure to unsupported adjustments. The same records also give sales reps and RevOps access to the basis finance uses for accruals.
For reps, a deal-level statement shows which contract contributed to the payout, which rule applied, and how attainment affected the result. That visibility reduces the need for shadow spreadsheets. Finance can ground its accrual estimate in the same underlying transactions rather than a top-down approximation that later requires a large true-up. RevOps and management can assess cost of sales by plan type, accelerator impact, and clawback frequency before those signals disappear into payroll totals.
As plans change, structured rule versions let reporting workflows change with them without having to rebuild the compliance infrastructure from scratch. New tiers, SPIFs, and renewal structures remain connected to dated calculation rules. Past results keep the context and evidence that supported them at the time. Finance gains a dependable basis for accounting, while RevOps and sales gain a usable explanation of compensation outcomes. The operational asset is a shared source of truth that connects the contract, the commission, and the financial result.