How Mid-Market SaaS Finance Teams Evaluate Commission Software After Spreadsheets Break Audit Requirements
Finance teams need deterministic calculations and locked audit trails, not spreadsheet flexibility.
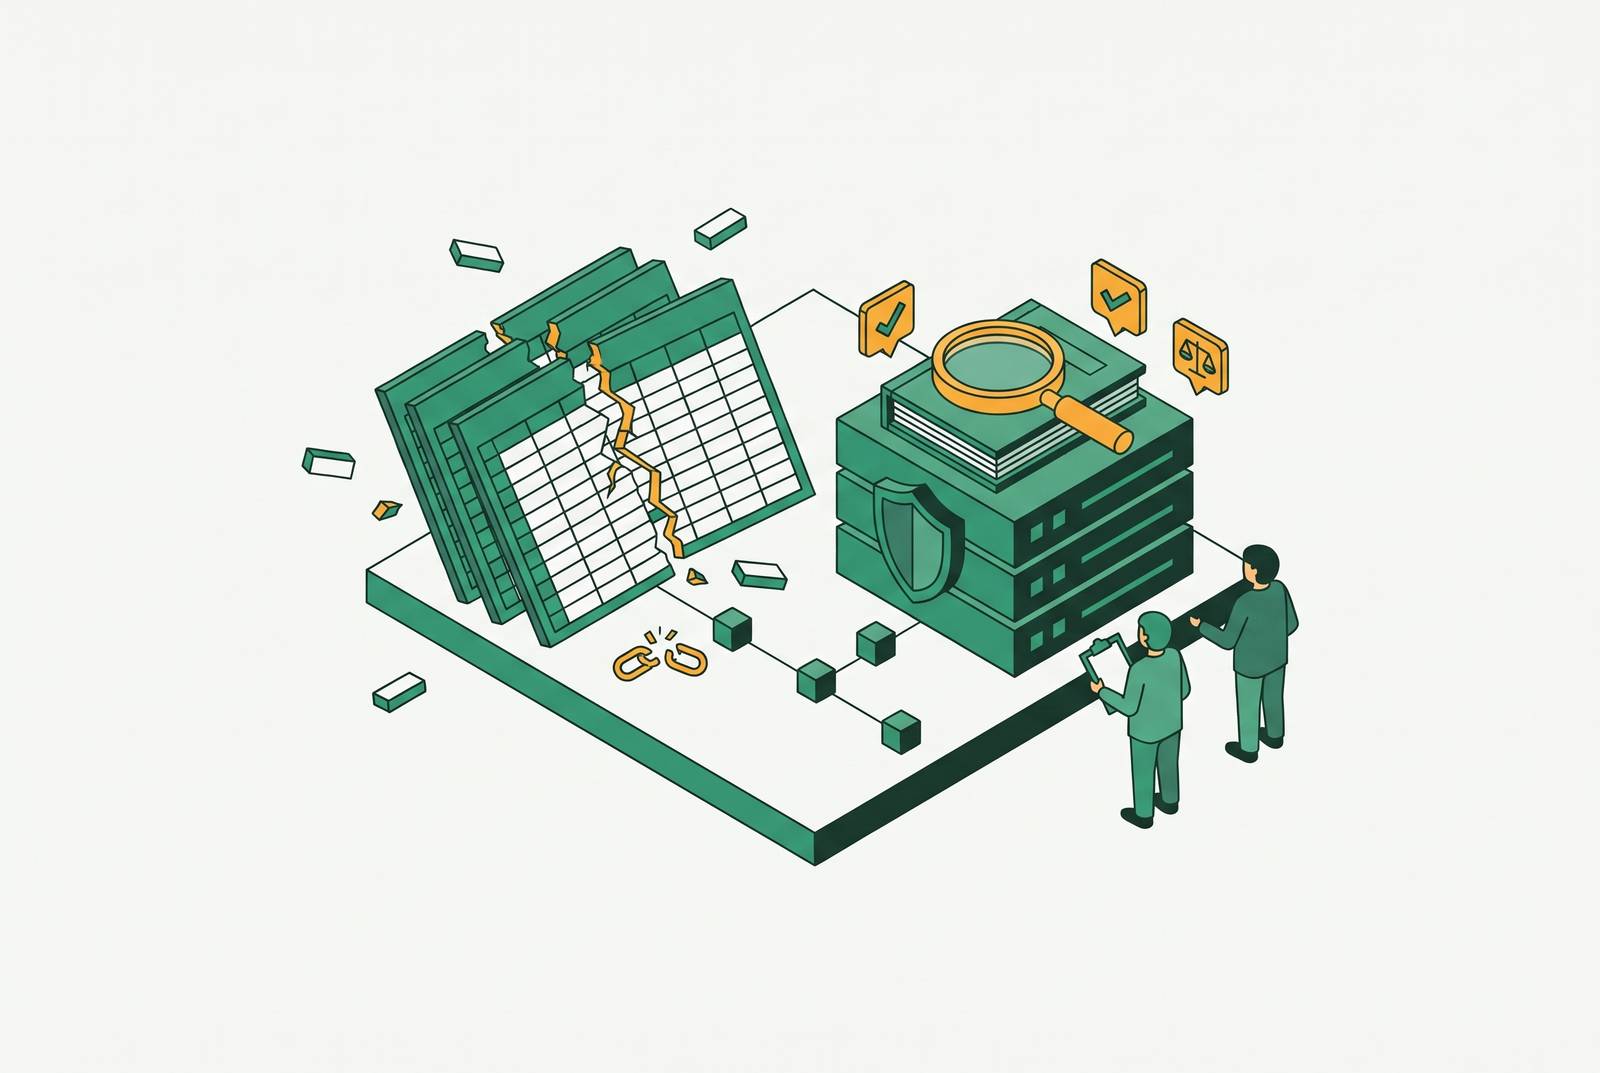
Commission software for mid-market RevOps and Finance teams should be evaluated first on deterministic calculations, native ASC 606 support, and enforceable audit controls. Once spreadsheets lose deal-level attribution or cannot preserve approved pay periods, ease of use is no longer the leading criterion. This article explains how finance teams turn those failures into a controls-based scorecard, with integration, rep visibility, pricing, and implementation risk assessed against the same standard of defensibility.
Why spreadsheet-based commission management becomes an audit liability as SaaS companies scale
Commission plans grow more complex faster than spreadsheets can safely handle. SaaS compensation plans accumulate multiple roles, overlay reps, SPIFs, accelerators, thresholds, territory rules, product multipliers, and mid-year adjustments. Each addition introduces conditional logic that spreads across tabs, references, and hidden formulas. A single incorrect reference can cascade through the model without becoming visible until a payout is wrong or an auditor requests its supporting schedule.
Shared ownership makes that structure more fragile. Rates may change in one copy while new reps appear in another, leaving neither complete and both treated as authoritative. Meanwhile, CRM exports that collapse transactions into per-rep totals preserve the payout number but discard its deal-level attribution. That distinction separates a payment worksheet from a defensible accounting record. The architecture cannot reliably preserve rules, transaction detail, and authoritative versions as the organization grows.
How spreadsheet commission management breaks ASC 606 traceability and audit defensibility
ASC 606 and ASC 340-40 require incremental costs of obtaining contracts, including sales commissions, to be capitalized and amortized over the expected period of benefit. For a lump-sum commission on a multi-year contract, finance must connect the payment to a deferred commission asset and its amortization schedule. The expected benefit period may extend beyond the contract term when renewals are anticipated. Finance needs the underlying contract attribution to support the accounting treatment.
Contract changes make that traceability more demanding. Mid-term seat upgrades and early terminations require the remaining asset balance to be recalculated, while early termination requires the remaining balance to be accelerated to expense immediately. Shared-file version history does not, by itself, establish a defensible record of the relevant changes across hundreds of revisions. The close process also needs an approved endpoint. Without locked, approvable pay periods, finance cannot show that the commission figure posted to the GL is complete and can be reproduced, so accruals rely on records that can still change.
The operational costs that accumulate before the audit crisis arrives
Unstable calculations affect more than the supporting schedule. Finance is unsure of its accruals, and some organizations overaccrue to make up for that, which adds tension during close. Reps who distrust payouts build private tracking spreadsheets that rarely align with the official model and consume selling time. The CFO Shortlist Buyer's Guide identifies this shadow accounting as the clearest signal that a team has outgrown spreadsheets. Disputes then generate retroactive adjustments without a clean record of who changed what or why.
RevOps absorbs the reconciliation work behind those disagreements. The monthly commission run can become a multi-day process dependent on one analyst, leaving the team exposed when that person is unavailable. A wrong close date, deal owner, split, or product line affects pay, but correcting the payout in a spreadsheet leaves the CRM field unchanged. The same error can therefore return next cycle, adding work until a dispute spike, close failure, or audit question exposes the accumulated weakness.
How do finance teams evaluate commission software after an audit failure?
An audit failure shifts evaluation from convenience to controls. Familiar workflows, easy migration, and a polished interface matter less when finance cannot produce a supporting schedule. An auditor must be able to trace a reproducible calculation from the deal through the payout to the amortization schedule. Finance therefore leads the review. This changes vendor qualification because strong rep features or quick setup cannot compensate for missing locked periods, change history, or native amortization support.
The calculation engine — why deterministic, auditable computation is the first requirement
A deterministic engine produces the same output from the same inputs. For commissions, that means crediting rules apply consistently to every transaction rather than depending on column order or a hidden lookup tab. Finance must be able to identify the deal, rule, and rate behind each amount, with transaction-level attribution preserved. Automation alone establishes neither property.
Historical reproducibility also depends on versioned plan logic. The engine must handle splits, draws, accelerators, tiers, clawbacks, overlays, team and manager credit, multi-currency, and effective-dating without consultant rework. Those requirements are not merely a measure of plan flexibility. A prior period can be reproduced exactly as calculated after the plan has changed only if those requirements are met. The buyer's guide recommends demanding a payout-accuracy SLA in writing, making a vendor's willingness to stand behind calculation accuracy a contractual test.
ASC 606 and SOX controls — the compliance capabilities that separate finance-grade platforms from comp tools
Native ASC 606 and ASC 340-40 handling connects commission capitalization and amortization schedules directly to payout data. It must also handle contract changes and early terminations, recalculate the asset balances that remain, and create the correct reversal entries for clawbacks. A separate Excel amortization model preserves the original dependency. For finance-led evaluation, native handling is therefore a qualification requirement rather than a premium feature that can be traded against interface quality.
SOX-grade controls govern how those records become authoritative. Locked pay periods keep approved calculations from being changed without a record, while documented amendments show who is responsible when changes are needed. Plan changes need a clear approval chain that logs timestamps. Segregation of duties must also prevent the person configuring a plan from approving payouts. Together, these controls replace the informal authority of a renamed file or a Slack message with an enforceable approval process.
Security belongs in this qualification stage as well. SOC 2 Type II certification and role-based access controls are baseline expectations to confirm before shortlisting. Compensation data also requires encryption in transit and at rest, org-scoped tenancy, and a strict policy against using customer data for model training. These protections address the sensitivity of individual earnings records. They do not, however, make an incorrect source record accurate, which leaves the quality of incoming data as a separate requirement.
CRM data quality as the unglamorous prerequisite to trustworthy commission automation
A deterministic engine can calculate the wrong payout perfectly. Close dates, deal owners, splits, and product lines originate in the sales process, but each also determines compensation. When those fields are wrong, even advanced calculation and accounting controls cannot fix the facts in them. Automation can instead move disputes from the formula to the deal data, where the cause is harder to diagnose and fix. This is the strongest objection to treating software deployment alone as the solution.
The practical response is parallel CRM hygiene work. Evaluation should establish whether a platform surfaces data problems rather than concealing them and whether it fits existing CRM workflows. A CRM connection or file upload should let work start while integration is still under way. Integration must ultimately close the accounting loop. Write-back to CRM and a clean GL export for accruals connect commission operations to the systems of record rather than leaving corrections isolated inside another tool.
Rep visibility and dispute reduction as finance controls, not just sales perks
Deal-level rep visibility is a finance control because it reduces the opacity that produces disputes and retroactive adjustments. A statement that shows credited deals, applied rates, and the plan version used lets reps check their pay against the official calculation. That transparency addresses the source of shadow accounting. Its value is therefore tied to the integrity of the commission record.
When there are fewer disputes, there are fewer reasons to reopen approved periods. That relationship gives real-time earnings, quota progress, and deal-level statement detail a place in a finance-led evaluation. An earnings estimator also helps reps understand what they can expect to earn. Visibility supports approval governance and calculation controls by reducing the disagreements that would otherwise require finance to reconcile competing records and amend prior payouts.
Pricing structure and implementation risk as evaluation criteria finance teams often miss
Commercial structure can introduce risk after capability screening succeeds. Per-user and per-payee pricing increases software cost as the team hires, while plan-based pricing scales with compensation complexity. Opaque enterprise quotes make that comparison harder. Finance therefore needs to assess both what drives the bill and the initial amount.
A multi-month implementation for a mid-market plan can signal a mismatch between the tool and the buyer's needs, with transition risk potentially exceeding the spreadsheet risk it was meant to remove. If comp ops needs support tickets or professional services to change plans, correct crediting, and run cycles, the organization now relies on the vendor as it once relied on an analyst. AI-assisted plan building can reduce setup time by extracting logic from existing compensation documents, but human review and approval must remain part of configuration.
Vendor durability also affects the practical value of controls. Repeated layoffs, post-acquisition product churn, and weak real-world commission references are warning signs, as are missing documented ROI or customer-success structures. ICM added to a planning tool needs credible commission references. These checks complement, rather than replace, the technical qualification. A platform still needs clean accounting support and GL export even when its implementation proposal and the terms of the deal look good.
The complete controls-based scorecard — how to weight each criterion when finance leads the evaluation
The scorecard should rank requirements in tiers so that strong optional features cannot make up for missing controls. Tier 1 contains disqualifying requirements, including deterministic and auditable calculation, a written payout-accuracy SLA, and native ASC 606 capitalization and amortization. Full change history, data lineage, plan approvals, segregation of duties, and locked pay periods belong here too, together with SOC 2 Type II certification and role-based access controls. A vendor that fails one does not advance because it offers a better rep dashboard.
Tier 2 distinguishes the platforms that pass those gates. Native Salesforce/HubSpot connections, ERP/HRIS and data warehouse integration, CRM write-back, and clean GL export determine how well the platform fits existing operations. ERP and HRIS connections are especially relevant where commission touches employee records. Deal-level statements and an earnings estimator help reps check their pay, while no-code or low-code administration cuts the need for professional services. Accrual reporting and self-service finance dashboards complete this tier by giving finance usable outputs beyond rep-facing statements.
Tier 3 tests whether a platform that has passed the checks will be practical to start using and keep. Pricing needs to be assessed against headcount and plan complexity, implementation against mid-market scope, and vendor stability against acquisition history, roadmap continuity, and real-world customer references. Security remains a final contractual and operational check. Before signing, finance should check that encryption, org-scoped tenancy, and the ban on training models with customer data meet the same standards it uses for payroll. Commission statements are individually sensitive compensation records, and the buying decision must treat them that way.